A person who has been tax resident in Italy for at least six of the last ten years, owns shares or a business worth €800,000 or more and takes a job in Lisbon or Madrid would owe the Italian state 26 percent on gains never cashed in. That is the core of the exit tax in Article 17 of the draft 2027 budget. I think it is the wrong way to tax anyone, and its deferral rules look unlikely to survive European law.
Table of contents
A bill for leaving
The draft applies to moves of tax residence taking effect from 1 January 2027. The taxable gain is the difference between market value and the tax cost on record, on assets and rights worth at least €800,000. Payment is due within 180 days. Bank deposits are left out, and government bonds are taxed on a reduced base that works out to 12.5 percent effective.
Anyone moving to another EU country, or to a country with a tax cooperation agreement, can defer. The price is half the tax up front plus a guarantee. Deferral runs up to five tax periods for EU destinations and up to ten for other qualifying countries.
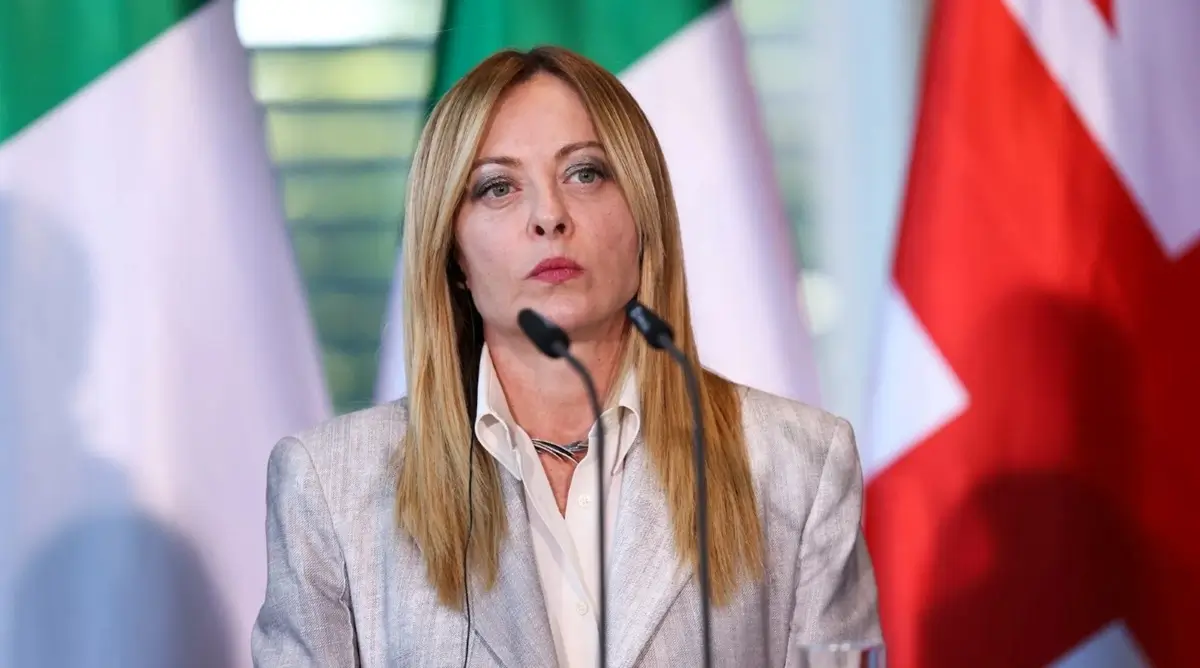
The Council of Ministers signed off the budget package on 28 October, and Article 17 went to the Chamber of Deputies on 30 October. Parliament must pass the budget by the end of the year, and the article can still be amended. The Telegraph called the measure a “surprise policy, which was not trailed in advance”.
A small exit tax with a loud signal
The technical report attached to the bill puts the revenue at €3.37 million in 2027 and €6.74 million a year from 2028 to 2031. The whole budget package is worth about €26 billion, so the exit tax would raise less than 0.03 percent of it.
Read also: Europe should tax billionaires on what they emit
A measure that brings in so little reads, in my view, as a message to wealthy residents about who owns the gains they built up in Italy. Federico Salmoiraghi says the text “appears poorly defined, leaving considerable room for doubt and interpretation”.
The EU’s top court has seen this before
In de Lasteyrie du Saillant (Case C-9/02, March 2004) the EU Court of Justice found that France’s exit tax infringed freedom of establishment. According to IMI Daily, the court also held that making deferral depend on guarantees was a restriction in itself.
The six-of-ten-years test and the €800,000 threshold in the Italian draft follow the French template. French rules today allow deferral for EU moves without any collateral requirement. Rome would demand more than Paris does, after a ruling that went against France.
A guarantee requirement for moves inside the single market is, in my view, the part of the draft most exposed to a challenge. The 50 percent payment up front makes the burden heavier, and the tax would be charged on a value that a falling market can erase before any sale.
Tax the gain when it is real
A state can reasonably want a share of gains that grew while the owner lived under its laws. Collecting that share when the asset is sold asks the leaver for no cash today, needs no guarantee and puts the emigrant in the same position as a neighbour who stays. Italy can design a rule like that and negotiate the information-sharing it needs with the destination countries.
Read also: EU adds €2 parcel fee to €3 duty
The draft takes the other road. It charges for a profit that exists only on paper, at a moment when the taxpayer is packing, and it asks for collateral against a market that may fall before any sale. A founder with a business worth €800,000 and little cash is the person this rule will hurt first.
Italy can have a tax on gains, or it can have a toll at the border. Article 17 is the toll, and the Chamber should strike it before a court does.
SOURCES & METHOD
How this article was made. The article rests on four sources, and none of them is the text of the bill itself. Which legal article carries the tax is reported differently in the sources and is left out.
Sources
- IMI Daily: Italy Budget Bill Proposes 26% Exit Tax on Residents Leaving With €800,000 or More (31 October 2026) – rate, threshold, deferral terms, revenue estimate and account of the 2004 ruling.
- Parameter: Italy Targets Millionaire Emigrants with New 26% Capital Gains Levy (2 November 2026) – mechanics, deferral, parliamentary timetable and the French comparison.
- The Telegraph via Yahoo: Meloni targets Italy’s wealthy with exit tax (1 November 2026) – rate, threshold and the description of the policy as unannounced.
- Brussels Signal: Italy approves 2027 budget (29 October 2026) – cabinet approval on 28 October and the year-end deadline.